The value of having the right team behind your business

The value of having the right team behind your business

Building and growing a successful farming business takes more than hard work and ambition. It also takes good decisions, sound advice and the right people around you.

As farming businesses grow and evolve, so do their financial and strategic needs. What starts as a straightforward lending relationship can develop into more complex decisions around business expansion, capital investment, succession and long-term planning.

Having access to the right expertise at the right time becomes increasingly important.

One trusted adviser. A whole team behind you.

At SproutAg, we believe there’s real value in combining a strong personal relationship with the knowledge, experience and resources of a broader team.

Our clients work directly with advisers who understand their businesses, their goals and the challenges and opportunities that come with agriculture. Behind those relationships sits a connected team with specialist expertise across agribusiness finance, equipment finance, succession planning and family business advisory.

This means clients benefit from a dedicated adviser who knows their business, backed by the collective knowledge, connections and experience of the wider SproutAg team.

It’s an approach that allows us to bring together different perspectives and specialist knowledge, while maintaining the personal service and independent advice our clients value.

Growing our business to better support yours

Over recent years, SproutAg has continued to grow, expanding into new regions, welcoming experienced people to the team and strengthening our specialist capabilities.

But our growth isn’t simply about having more offices or a larger team. It’s about what that growth enables us to deliver for our clients.

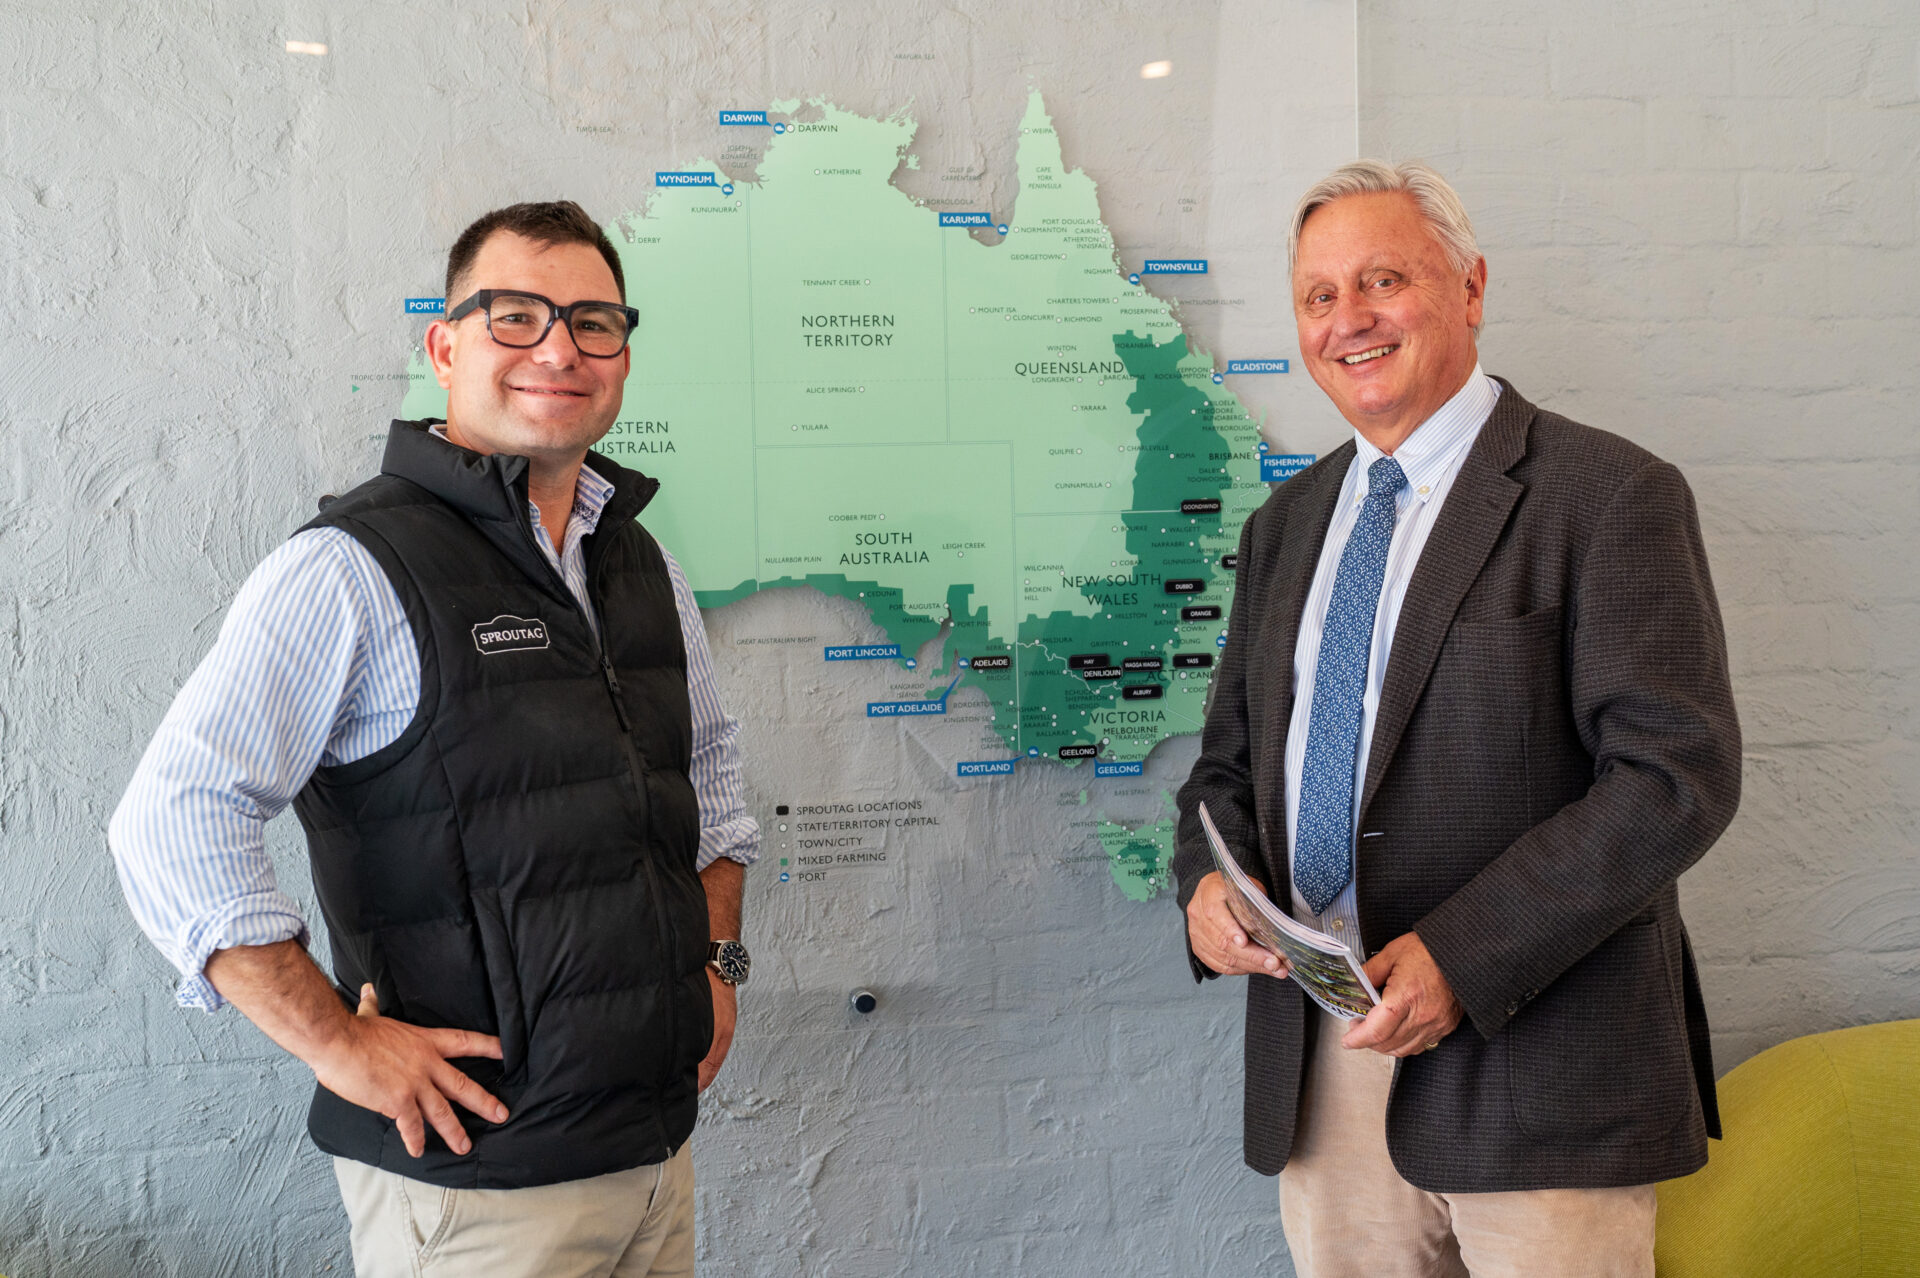
Our recent expansion into South Australia and Western Victoria has strengthened our regional presence, bringing additional local knowledge, industry relationships and experience into the business. At the same time, the establishment of Sprout Equipment Finance has expanded our equipment finance capability, providing greater specialist support to clients across agriculture and other regional industries.

Together, these developments reflect our commitment to building a stronger, more connected team with the expertise and resources to support clients through a broad range of financial and business decisions.

As our regional footprint and team continue to grow, so does our ability to support the farming businesses and families we work with.

Looking ahead

Whether you’re looking to expand your operation, invest in new opportunities, review your finance structures or plan for the next generation, having the right people around you can make a significant difference.

At SproutAg, our focus remains on building long-term relationships, understanding what matters to our clients and providing independent, tailored advice to help them make confident decisions for the future.
What is your banking really costing your business?

With the RBA cash rate increasing again, the cost of finance is firmly back in focus for farming businesses and agribusinesses.

When rates move, it is natural to look first at the interest rate being charged by your bank. You might also ask: What is my margin? Is it competitive? Could I get a better rate elsewhere?

These are important questions, but they don’t necessarily tell you what your banking is really costing your business.

Banking structures and letters of offer have become increasingly complex. To properly review your finance, you need to look beyond the headline interest rate and margin and understand the total cost of your banking.

Look beyond the margin

Your margin remains an important part of your finance structure, but comparing margins alone can be misleading.

The way banks calculate and present interest rates can vary. Depending on the facility, a rate may be based on a market rate plus a margin, while other facilities may use a bank reference rate with an additional customer margin applied.

That means two facilities with what appear to be similar margins may have quite different overall costs.

Then there are the costs sitting outside the interest rate itself.

Depending on your facilities and bank, these can include:

  1. line or facility fees
  2. unused limit fees
  3. establishment or application costs
  4. account and transaction fees
  5. other ongoing banking costs.

Rather than asking only “What interest rate am I paying?” or “What is my margin?”, a better question is: “What is the total annual cost of my banking?”

Understand what you’re paying for

The next step is understanding whether the facilities you’re paying for remain appropriate for your business.

A working capital facility with a higher limit provides additional flexibility, for example, but it may also attract line or unused limit fees. That doesn’t necessarily mean the facility is poorly structured. The additional capacity may be valuable to the business, particularly where seasonal conditions or cashflow requirements can change quickly.

The important thing is knowing what you’re paying, why you’re paying it and whether the structure still makes sense for your business.

The same principle applies across term debt, working capital and equipment finance. Each facility should be considered as part of your overall finance structure rather than simply looking for the lowest individual rate.

Look beyond the headline rate

While understanding the total cost of your banking is important, there are other factors to consider as part of a review.

Fixed and variable facilities can provide different levels of certainty and flexibility. Before fixing a rate, it is important to understand potential break costs and any financial implications if you want to reduce or repay the facility earlier than expected.

If your business holds cash in at-call accounts or term deposits, review the interest being earned. As lending rates increase, it is worth making sure your deposit rates remain competitive too.

Equipment finance should also be considered as part of your broader finance structure, with repayments and facility terms aligned to the cashflow requirements of the business.

A competitive finance structure should balance cost with the flexibility the business needs today and may need in the future.

Be proactive about working capital

Cost is only one part of managing finance well. Having the right facilities available when you need them is equally important.

Understanding your future funding requirements is just as important as reviewing what you’re paying today. Keeping your cashflow forecasts up to date and reviewing working capital limits early gives you time to approach your bank and consider your options, rather than seeking additional funding when cashflow is already tight.

Three things to consider when reviewing your banking

  1. Understand the total cost

Look beyond the headline rate and margin. Consider interest, line fees, unused limit fees, account fees, establishment costs and other ongoing charges to understand what your banking is costing your business each year.

  1. Review your structure regularly

A facility that suited your business several years ago may not necessarily suit it today. As a general guide, we recommend undertaking a comprehensive review and market comparison at least every three years, or sooner if your business or funding requirements have changed.

  1. Compare like with like

Different banks can structure and price facilities differently. When comparing options, make sure you’re looking at the total cost, facility structure and flexibility rather than simply comparing the quoted margin or interest rate.

Know the true cost of your banking

With interest rates moving higher, now is a good time to take a closer look at your banking.

But don’t stop at the interest rate.

Understanding the total cost of your facilities, how those costs are calculated and whether your finance remains appropriate for your business can give you a much clearer picture of your position.

At SproutAg, we work with farming families and agribusinesses to independently review and benchmark their finance structures, helping them understand the true cost of their banking and whether their facilities remain competitive and fit for purpose.

What if you need a short-term funding increase this late in the season?

This year, fingers crossed, the season is looking reasonably positive across many areas, particularly through the southern mixed farming belt. For many producers, however, the next month or so will be important.

With talk around El Niño and the potential for warmer and drier conditions through spring, the question is how quickly the season could turn following a relatively mild winter.

In some areas, people are saying they’re only a couple of well-timed rains away from a strong finish. If conditions allow, some producers and growers may choose to put additional weight on livestock, hold off on sales such as wool to manage the timing of income, or store grain on farm post-harvest.

Decisions like these can create higher working capital requirements, over and above what may have originally been budgeted.

Before you increase the spend, understand the return

The first question shouldn’t necessarily be how do I access more money? It should be is spending the additional money going to generate an appropriate return?

Take livestock as an example. Holding animals for longer may deliver additional weight and potentially greater sale proceeds, but there is also the cost of feed, along with the market and seasonal risk associated with carrying those animals for longer.

Before committing additional capital, work through the numbers. What is the potential upside? What will the additional funding cost? How much margin is there if commodity prices move? And what happens if the season turns?

It’s ultimately a risk and reward decision, and understanding both sides of that equation is important before increasing expenditure.

If you need more working capital, don’t leave it too late

Once you’ve established that the opportunity stacks up commercially, the next consideration is how you fund it. If your existing overdraft or working capital facility isn’t going to be enough, start the conversation early.

A few things to consider:

  1. Allow more time than you think you’ll need. Don’t wait until you’re approaching your existing limit before speaking with your lender or finance adviser.
  2. Ask for enough. Look beyond the immediate expense and forecast your cash position through harvest, livestock sales or the point at which the facility is expected to reduce. If there is uncertainty, building in some buffer may be more practical than having to return for another increase several weeks later.
  3. Have your numbers ready. An updated cashflow, current trading position and a clear explanation of why the additional funding is required can make the conversation much easier.
  4. Know how the additional debt comes back out. A short-term increase should have a clear purpose and an expected repayment pathway, whether that’s grain sales, livestock proceeds, wool income or another known cash inflow

Working capital should give your business the flexibility to take advantage of an opportunity, rather than becoming a constraint when you need it most.
If you’re looking at the remainder of the season and think your existing facilities may not comfortably carry the additional spend, now is the time to start the conversation.

The most change in Agribusiness Finance since the GFC.

The most change in Agribusiness Finance since the GFC.

Slow, Slow, Slow.

Slow seems to be the common feedback we’re receiving across the board as we place transactions with various lenders in the industry. In general, we are seeing a withdrawal of services from rural lending with one bank ‘top heavy’ in the beef sector limiting them from taking on new deals, one bank going through a major restructure, and another agribusiness player being purchased. In addition to these industry movements, we have also observed a large reduction in the branch network that impacts many rural clients. Based on current trends, in the medium term, unless you have lending over $5million, it is likely that you might not have a dedicated relationship manager in the next 5 years.

So, why are Agribusiness divisions going through large restructures?

Restructures and consolidation across the industry have been happening for some time. We’re seeing Agribusiness divisions undertaking restructures because in comparison to previous years, they’re not seeing lending books or future profit returns grow as quickly as they have. It is estimated that the main cost to an Agribusinesses Division Bank are the people (approx. 80%), and the only way to increase profitability is to reduce people and digitise their offering. For clients requiring less than $5milion in lending, it is anticipated that their communication channels will be through a call centre or over the phone with their manager. These changes will be made to ensure that future profits are delivered as the system growth reduces in future years due to a deliberate slow down by the RBA.

Why are bank branches closing?

Many banks are shutting branches because of a reduction in face-to-face cash transactions by retail customers. This doesn’t have a direct impact on Ag lending, but more of an indirect impact. As business owners, it can be difficult to open new accounts with trusts and companies involved, and often this requires face-to-face expertise that is usually associated with an in-person meeting.

Why do banks stop lending in certain sectors?

At times, banks grow too quickly within a sector, and this is when we see restriction on lending to new clients put in place. Banks may follow a one client in, one client out scenario, and this is currently what we’re seeing, because they have grown too quickly through ‘boom year’s’.

Acquisition making change in the Ag lending.

One major bank is currently going through the process of buying another Regional Bank with around 4 billion in Ag lending. This acquisition will likely generate a large amount of change, particularly in the Queensland market. This change will be around people and the consolidation of those businesses overtime.

As we navigate these changes, we recommend to our clients:

  • It’s never been so important to properly present your business to lender.
  • It’s never been more important to be on the font foot and proactive around finances.
  • Given the turmoil in agribusiness lending, it is critical to get another option right now.

Finding the Balance: Growth, Liquidity and Control

The nose in, hands out approach.

Different lifestyles and stages of life often drive the succession conversation. Generally, we see two different generations working together with different cashflow needs.

Typically, the existing or the current generation may be aged between 50 – 80yrs of age and tend to take less risk to allow more time for family and travel. To achieve this lifestyle, they will need to increase their cashflow by way of dividends, salaries or drawings. In contrast to this, the next generation is wanting to grow the business, and growth of any kind requires cashflow.

With different generations and life stages comes different business strategies based on what each generation is working to achieve. As an advisory business, we spend a lot of time working with clients to develop and agree upon an intergenerational business strategy, often working through tension and tough conversations around reinvesting back into the business and when to take cash out of the business.

Developing and agreeing upon a business strategy is a normal and difficult step to take, as there can be an underlying, natural conflict between the generations before taking the business and family relationships into consideration.

Ideally, we look for a nose in, hands out scenario from the existing generations, where they are adding value, involved where they want to be, and are more strategic, however they have their hands out of the day-to-day business. This positioning will allow the next generation to step up and execute the business activities and get the day to day done their way.

To execute this approach, families need to set the guardrails and provide governance to the next generation and outline what is important to them.

When working with families, we start by developing an Owner Strategy Statement, with three key steps:

Step 1. Define Your Purpose

  • Defining the purpose of your family business.
  • Why do you want to own your business together as a family?

Step 2. Set Your Owner Goals

  • Specify your concrete goals.
  • A great exercise we do to determine goals is to review the Owner Strategy triangle. You can choose to prioritise any two of the goals at the expense of the third.

Step 3. Create Owner Guardrails

  • It’s time to translate your purpose and goals into specific measurements that can be used to make decisions.
  • Guiderails can be financial or non-financial.

Once a family’s strategy and guardrails are set, the next generation will be able to take the lead on the business knowing what’s important to both generations.

To create an Owner Strategy Statement, contact us today; Contact Us – Sproutag

Get Yourself Organised for the Year Ahead

“If you fail to plan, you are planning to fail.”

As farming businesses grow, the level of planning needs to grow with the business, so the planning process becomes much more important and complicated.

At SproutAg, one of our mantras to our clients is to “get organised”. When we have this conversation with clients, we’re quite direct because we see first hand the difference that being organised can make to a farming business and the opportunities that can arise.

2023 saw a large variance in commodity prices and seasonal fluctuations that saw working capital requirements and the cost of interest much higher than anticipated. Currently, we are still facing inflation in Australia, the cost of goods has not come down and we anticipate that interest rates will remain high. But within all of this, opportunities have arisen, and it is the well organised family businesses that can take advantage of these opportunities.

To get your family business organised, these are our top three areas for you to consider in 2024:

  1. Getting through 2024 and what to consider
  2. Planning for growth with positivity
  3. Family business planning and generational planning

Getting Through 2024

The first step to getting through 2024 is to review 2023, and identify where your family business is at. This is achieved by using the ‘Where did the money go’ tool from our AgPro program. Following this review, you can complete three cashflow forecasts for the year, before setting up appropriate funding to achieve success.

Your first goal in working capital is to set funding limits that will cater for most scenarios, where you will only need to go back to the bank once as opposed to hat in hand later in the season asking for more. It is important to factor in higher costs and lower revenue, and to set your debt limits up one bracket for the year ahead. What we find with clients is that working capital increases were quite frequent towards the end of 2023, and they take time, so it is important to have the philosophy to tackle this only once in 2024. This is also the time to consider and work in small opportunities for your family business, i.e. livestock purchases or other opportunities.

For additional help and tools talk to your local SproutAg adviser.

Planning for Growth

If you’re planning to develop your country or farming infrastructure or looking to buy new machinery or another property, get organised and don’t wait until the last minute – plan for the acquisition and development and get the acquisition pre-approved ahead of time. Getting pre-approval can take a considerable amount of time, so it is important to get your ducks in a row early in the year to make the process easier.

It’s important to remember that growth often comes from careful planning.

Family Planning and Generational Planning
Your third area to consider in 2024 is family business planning and generational planning. You need to start by asking yourself, “What are my asset policies in the business?” What we mean by this is, you have your farming assets, and you may have three children. How do you think about your assets longer term and how do you start to set yourself up so that one day you may not rely on the day-to-day farming or trading entities.

Family businesses who do well with succession planning and transitioning start the process early, giving themselves time. There is no better time to start your longer-term planning than today!

Here are some key questions to ask yourself to get started:

Do I want my family business to continue to the next generation?
What are your family’s long-term (10-30 year) goals?

Once these long-term goals have been identified, we break it down and look at the next three to ten years:

  • Where do you want to live?
  • What do you want to be doing?
  • What will your lifestyle look like?
  • What will your asset policy look like for working and non-working family members?
  • How do you communicate and set expectation early?

Find out more about our succession planning guide here.

To get your finance organised for 2024, our biggest advice is to be proactive and do something about it!

Getting Stuck in Farm Succession Planning and How to Get Out.

Getting stuck in farm succession planning and how to get out.
We often work with families on farm succession planning who’ve frustratingly been going around in circles for years and have become stuck in the decision-making process. When we start the conversation, it’s soon discovered that there may only be a few small changes to make and that it is easy to become unstuck. For some families it may take a significant catalyst to commence their succession planning i.e. a health diagnosis, serious fallout or a long-held disagreement.

When working in a family business, you’re managing blood relations, finances and a business, and it can often be difficult to get the combination of the three correct. When there is deep respect and love for family members involved, the conversations can be more difficult to have.

What do we mean by getting stuck in farm succession planning?
Families can often get stuck in the decision-making process, when issues are avoided or when discussions go around in circles, sometimes for years, or even decades. An issue may be approached, but if there are disagreements or misalignments it can easily become stuck.

What does being stuck look like?
Being stuck can take many forms, an issue may never be spoken about, or if it is, there is constant conflict over the smallest discussion.

What are the consequences of being stuck?
In our experience, ‘becoming stuck’ not only has consequences on the business, but also strains on family relationships that continue to escalate and mental health issues that arise from unresolved problems year after year.

What can happen to the business?
When families aren’t aligned, a business can go around in circles and major decisions are delayed or put on hold. This can affect a business’s ability to make acquisitions or further develop the operation with new or innovative ideas limiting the business’s productivity.

Commonalities and tools to manage being stuck.
Common areas where we see clients stuck and unable to progress with succession planning are:

Common Barrier Number One:
When an existing generation worry that there will be a divorce event in the next generation, and that they will lose their wealth. As a result, the decision-making process grinds to a halt, sometimes before it even starts.

This scenario may take the SproutAg team two or three conversations to understand that this possibility is seen as a roadblock to the current business owners in that family. While there are many tools available to mitigate the risks for family members against family law events, family members can feel uncomfortable raising the topic, which leads to the family being stuck on an issue they don’t feel comfortable discussing. Each family and family business structure is different, and to enable future growth and to protect the broader family there are different tools available including:
– Marital deed or prenup (although these are not as common in Australia)
– Sunset clause
– Registering a caveat and/or second mortgage.

*Note that every circumstance is different, and that these tools are not recommended for individualised scenarios. For individual advice, reach out to the SproutAg team.

Common Barrier Number Two:
The existing generation wants to keep working on the farm and still be involved.
The next generation can often see the desire for the existing generation wanting to stay involved and not wanting to give up control or take on the next generation’s new ideas. These unspoken feelings can lead to family conflict and can cause families to become stuck. Often there are few roles and responsibilities that the existing generations wish to keep, however it is important to identify these early in the succession planning process and keep them at the forefront of the plan to ensure all parties are accountable.
– Meeting schedules
– Roles and responsibilities map.
– Future organisational chart.
– Employment contract with set roles and responsibilities.

Download a copy of our free succession planning guide on our website here.